
Spain's Housing Supply Crunch and Its Economic Ripple Effects
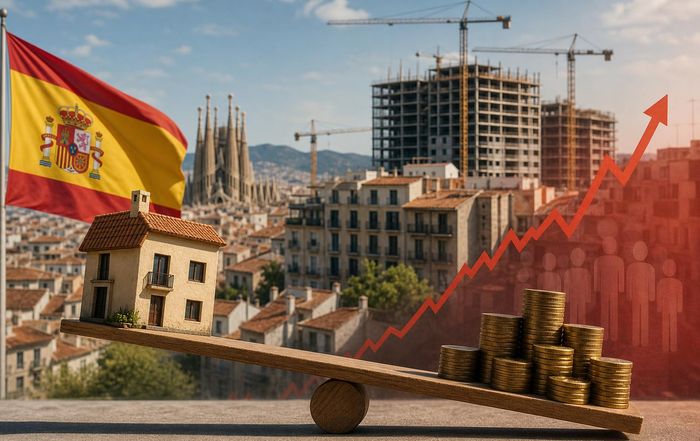
Spain's housing market has re-emerged as a central economic fault line. After a decade of digesting the excesses of the pre-2008 construction boom, the country is now facing the opposite problem: a structural shortage of homes in the places where people most want and need to live. That mismatch between demand and supply is pushing up rents and prices, reshaping labour mobility, feeding inflation, and forcing policymakers to rethink how housing fits into Spain's broader economic model.
This page examines what is driving Spain's housing supply crunch, how it is affecting households and the wider economy, and which policy responses and market shifts are starting to take shape.
From post-crisis glut to structural shortage
In the years leading up to the global financial crisis, Spain became a symbol of real-estate excess. At the peak, construction accounted for a large share of GDP and employment, and hundreds of thousands of new homes were built annually, especially along the Mediterranean coast and in suburban developments. When the property bubble burst, prices collapsed, developers failed, and a large inventory of unsold homes emerged, particularly in smaller towns and tourist regions with weak underlying demand.
Over the following decade, that apparent oversupply masked a different, slower-burning problem. Population and economic activity continued to concentrate in major urban centres such as Madrid, Barcelona, Valencia, Málaga, and Bilbao, while new construction in those cities lagged behind urbanisation and household formation. According to data from Banco de España and Spain's national statistics office INE, the country's total housing stock grew modestly, but much of the growth was in areas with limited job opportunities and weaker demand. Meanwhile, household structures changed: more single-person households, delayed but not abandoned plans to form families, and growing numbers of international workers and students all added to demand for urban housing.
By the early 2020s, the narrative had flipped. Instead of a glut, policymakers and analysts were warning of a shortage of habitable, appropriately located, and affordable housing in key job-rich regions. The European Commission and organisations such as the OECD began highlighting housing constraints as a competitiveness issue, not just a social one, noting that tight housing markets in Spain's major cities were constraining labour mobility and productivity. The pandemic briefly slowed demand in city centres, but that pause was short-lived; as tourism and migration rebounded and remote work settled into hybrid models, pressure on urban housing markets intensified again.
Why supply is failing to keep up
Spain's supply crunch is the product of multiple overlapping constraints rather than a single cause. On the physical side, the pace of new construction in the main metropolitan areas has not matched demographic and economic trends. Building permits in cities like Madrid and Barcelona remain below pre-2008 peaks, even as their populations and roles as service and technology hubs have grown. Large urban developments such as Madrid's "Operación Chamartín" (Madrid Nuevo Norte) have faced years of planning and legal delays, illustrating how slow the pipeline can be from concept to completed homes.
Regulatory and planning barriers are a core part of the story. Urban planning in Spain is largely managed at the regional and municipal level, producing a patchwork of zoning rules, density limits, and procedural steps. Industry groups and some economists argue that restrictive height limits, lengthy permitting processes, and frequent litigation over land use have made it hard to increase density in central areas or to bring new land into development at the pace required. Municipalities also face political trade-offs: existing residents may resist densification, while local governments rely heavily on property-related revenues, which can sometimes incentivise short-term decisions over long-term supply planning.
On the financial side, developers have faced rising construction costs, driven by higher prices for materials, labour, and energy. Tighter post-crisis lending standards and more cautious bank behaviour, overseen by the European Central Bank and national regulators, have made speculative building less common but also raised hurdles for new projects, particularly in the affordable segment. As interest rates rose sharply from 2022 in response to eurozone inflation, financing costs for both developers and buyers increased, further complicating the economics of new builds.
Investor behaviour has also influenced supply dynamics. Institutional investors and real-estate funds have been active in acquiring existing housing stock, especially in major cities and tourist hotspots, to operate as rental portfolios or short-stay accommodation. While these investments can professionalise the rental sector, critics argue that they can reduce the amount of housing available for long-term residents, particularly when properties are converted to tourist rentals. Platforms such as Airbnb and Booking Holdings have intensified competition for centrally located apartments, prompting several Spanish cities to impose stricter regulations on short-term rentals. At the same time, the growth of purpose-built student housing and co-living projects reflects how developers have targeted higher-yield niches rather than broad-based affordable housing.
The rental squeeze and its social consequences
The most visible symptom of the supply crunch has been the sharp rise in rents in major Spanish cities. Data compiled by national property portals and the OECD show that rents in urban centres like Barcelona and Madrid have risen significantly faster than average wages over the past decade, particularly for smaller apartments typically sought by younger workers, students, and lower-income households. This divergence has pushed housing-cost-to-income ratios higher, especially for renters, who often face more precarious employment and less savings than homeowners.
Young adults have been hit hardest. Spain has long had one of the highest average ages for leaving the parental home in Europe, and the combination of high youth unemployment, temporary contracts, and elevated rents has kept that figure stubbornly high. Surveys by organisations such as the European Youth Forum and Spanish think tanks indicate that many young people delay forming independent households or having children because they cannot secure affordable, stable housing. This has direct demographic implications in a country already grappling with low birth rates and an ageing population.
The squeeze is not limited to the largest metros. Tourist-heavy regions such as the Balearic and Canary Islands, the Costa del Sol, and parts of Catalonia and Valencia have seen local residents priced out of rental markets as demand from visitors, foreign buyers, and remote workers has surged. Seasonal workers in hospitality and agriculture often struggle to find adequate accommodation near their jobs, sometimes resorting to overcrowded or informal arrangements. Local authorities in some of these areas have warned that housing shortages are undermining the viability of essential services, as nurses, teachers, and police officers cannot afford to live near their workplaces.
Housing stress also has knock-on effects on inequality and social cohesion. Rising rents and prices disproportionately affect lower-income households and those without family wealth to draw upon for deposits or rent guarantees. Charities and NGOs report increased demand for emergency housing support and a rise in evictions due to rent arrears, particularly during periods of economic slowdown. While Spain introduced eviction moratoria at various points during the pandemic, those were temporary measures, and underlying affordability issues remain. The result is a growing perception that access to decent housing is becoming a dividing line between those with assets and those without.
How the housing crunch feeds into inflation and monetary policy
Housing is a key component of living costs, and Spain's supply constraints have made it a significant driver of inflation dynamics. Although owner-occupied housing is treated differently in official consumer price indices, rents and housing-related costs feed directly into measures of core inflation, which central banks monitor closely. As rents in major cities have climbed, they have contributed to underlying price pressures even when energy or food prices have moderated.
This has complicated the task of the European Central Bank, which sets monetary policy for the euro area as a whole. While Spain's housing market is only one piece of the eurozone puzzle, persistent rental inflation in several member states, including Spain, has been one reason core inflation has proven sticky. Tighter monetary policy, in turn, affects Spain's housing market in several ways: higher interest rates increase mortgage costs, which can cool demand for home purchases and dampen price growth, but they also raise financing costs for developers, potentially slowing new construction and exacerbating supply shortages over the medium term.
For households, the interaction between rents, wages, and interest rates is critical. In recent years, wage growth in Spain has lagged behind rent increases in key cities, eroding disposable incomes and consumption capacity. Higher mortgage rates have made it harder for renters to transition into homeownership, locking more people into a rental market where supply is constrained and rents are rising. This "trapped renter" effect can reduce household formation and delay life decisions, with broader demographic and economic consequences.
From a macroeconomic perspective, elevated housing costs can distort consumption patterns and savings behaviour. Households spending a larger share of their income on rent or mortgage payments have less to spend on other goods and services, potentially dampening demand in other sectors. At the same time, those who already own property may see their wealth increase as prices rise, reinforcing wealth inequality. Policymakers at Banco de España have warned that housing affordability pressures, if left unaddressed, could amplify economic volatility and complicate the transmission of monetary policy across different segments of the population.
Labour mobility, productivity, and regional imbalances
Housing supply is increasingly recognised as an economic infrastructure issue, closely tied to labour mobility and productivity. Spain's economy has been gradually rebalancing toward services, technology, and high-value-added sectors concentrated in a handful of metropolitan regions. Yet the very cities that offer the most dynamic job opportunities are often those with the tightest housing markets.
When workers cannot afford to move to where jobs are, or to live near their workplaces, labour-market efficiency suffers. Studies by the OECD and academic institutions such as Universidad Carlos III de Madrid have highlighted how housing constraints can reduce job matching, increase commuting times, and limit the ability of firms to expand in high-productivity locations. In Spain, anecdotal evidence from employers in technology, healthcare, and hospitality suggests that housing availability and cost are increasingly a factor in recruitment and retention, especially for mid-career professionals and international hires.
Regional imbalances are reinforced by these dynamics. Less dynamic regions with surplus housing stock may struggle to attract investment and talent, while booming regions face infrastructure and affordability pressures that can undermine their long-term competitiveness. The Spanish government has sought to address some of these imbalances through EU-funded recovery and resilience plans, including investments in digital and transport infrastructure and incentives for business development outside traditional hubs. However, without sufficient housing supply in growth areas, the full benefits of such investments may not be realised.
Remote and hybrid work offer some partial relief, allowing certain professionals to live further from city centres or in smaller towns while maintaining access to urban labour markets. Yet this trend can also create new pressures, as remote workers with higher incomes bid up housing costs in previously affordable areas, particularly attractive coastal or rural locations. The net effect on regional disparities is therefore mixed, and it underscores the need for coherent housing strategies at both national and regional levels.
Public finances, banks, and the construction sector
The housing supply crunch also has important implications for Spain's public finances, financial system, and construction industry. On the fiscal side, property-related taxes and transaction duties are a significant source of revenue for regional and local governments. Rising property values and transaction volumes in tight markets can boost revenues in the short term, but they also create sensitivity to any downturn in housing activity. Moreover, the need to invest public funds in social housing, rental support, and urban infrastructure places additional demands on budgets already constrained by broader fiscal rules and ageing-related spending.
Spain's banking sector, overseen by Banco de España within the European System of Financial Supervision, remains heavily exposed to real estate through mortgage lending and developer financing, though capital positions and risk controls have strengthened considerably since the last crisis. A sustained period of high prices supported by genuine supply shortages is less likely to produce the kind of abrupt correction seen in the 2008 bust, but it does present other risks. Affordability stress among borrowers, especially if interest rates remain elevated, could increase credit risk at the margins. At the same time, banks must balance prudential caution with the need to finance new housing projects, including in the affordable and social segments where returns may be lower but social needs are higher.
For the construction sector, the supply crunch represents both an opportunity and a challenge. Demand for new housing in major cities and high-growth regions is strong, and EU recovery funds have earmarked resources for energy-efficient renovation and new builds. Yet the sector faces capacity constraints, including shortages of skilled labour, rising input costs, and the need to comply with increasingly stringent environmental and energy-efficiency standards. Efforts to decarbonise the building stock, aligned with European Green Deal objectives, require investments that can raise upfront costs even if they lower operating costs over time. Balancing speed, affordability, and sustainability is becoming a central strategic question for developers and policymakers alike.
Policy responses: rent controls, public housing, and regulation
Spanish policymakers at national, regional, and municipal levels have begun to deploy a range of tools to address the housing crunch, with mixed reactions from investors, tenants, and economists. One of the highest-profile steps has been the introduction of a new Housing Law that allows regional governments to designate "stressed" rental markets and impose caps on rent increases for certain properties and landlords. Supporters argue that rent controls provide immediate relief for tenants facing sharp hikes, while critics, including some economists and industry groups, warn that strict caps can discourage new rental supply and lead landlords to withdraw properties from the market.
Alongside rent regulation, there has been renewed emphasis on expanding the stock of social and affordable housing. By European standards, Spain has a relatively small share of public or publicly supported rental housing, and much of the existing stock is concentrated in specific neighbourhoods built decades ago. The central government has announced plans, often in partnership with regional authorities and public entities, to mobilise public land, convert underused buildings, and incentivise the development of affordable rental units. The European Investment Bank and EU cohesion funds have also been identified as potential sources of financing for such projects, especially when they align with energy-efficiency and social-inclusion goals.
Regulation of short-term rentals has tightened in several major cities. Municipalities such as Barcelona have limited the number of tourist licences, increased enforcement against illegal rentals, and sought to channel more properties back into the long-term rental market. These measures have been controversial, with tourism and platform-economy advocates warning of negative impacts on visitor numbers and local businesses, while resident groups and housing advocates argue they are necessary to rebalance housing markets. The broader debate over how to manage tourism intensity and quality of life is likely to continue, particularly in coastal and island regions.
Land-use and planning reforms are also on the agenda. Some experts and business groups have called for simplified permitting processes, clearer zoning rules, and greater flexibility to increase density in well-served urban areas. Others caution that deregulation without strong safeguards could lead to environmental damage or poorly integrated developments. Striking a balance between enabling more supply and maintaining urban quality, green spaces, and infrastructure capacity is a central challenge for local planners.
Innovation, private initiatives, and emerging models
Beyond government action, a range of private and hybrid initiatives are experimenting with new ways to expand housing supply and improve affordability. Institutional investors, including pension funds and insurance companies, have shown interest in build-to-rent projects, which can add professionally managed rental stock if aligned with affordability goals. Public-private partnerships, where developers receive incentives or access to public land in exchange for commitments to deliver below-market units, are being explored in several regions.
New housing models are also emerging. Co-living spaces and shared apartments targeted at young professionals, students, and mobile workers are proliferating in cities like Madrid and Barcelona. These arrangements can offer lower per-person costs and more flexible contracts, but they also raise questions about long-term stability and regulatory oversight. Cooperative housing and community land trusts, while still niche in Spain compared with some northern European countries, are attracting interest among groups seeking more collective ownership structures and insulation from speculative pressures.
Technology is playing a role as well. Proptech platforms are improving transparency in rental and sales markets, helping tenants and buyers compare options and track price trends. Digital tools are streamlining parts of the permitting and transaction process. At the construction level, modular and industrialised building techniques are being promoted as ways to reduce costs and accelerate delivery, particularly for standardised affordable units. Research institutions and industry bodies, often in collaboration with universities such as Universitat Politècnica de Catalunya and Universidad Politécnica de Madrid, are exploring how to combine these innovations with low-carbon materials and energy-efficient design.
For international investors and businesses following Spain's broader economic outlook, these developments intersect with themes such as sustainable infrastructure, green finance, and urban resilience. Housing policy is increasingly seen not just as a social responsibility but as part of the enabling environment for investment, innovation, and long-term growth.
What Spain's experience signals for other markets
Spain's housing supply crunch is shaped by its specific history, institutions, and geography, but it also reflects wider pressures seen in many advanced economies: urbanisation, demographic change, financialisation of housing, and the constraints of land and infrastructure. For policymakers and investors in other markets, Spain offers a case study in how a country can swing from overbuilding and crisis to shortage and affordability stress within little more than a decade.
The Spanish experience underscores several broader lessons. First, housing cycles are long, and decisions made during one phase-such as tightening credit or imposing strict planning limits-can have delayed effects that become binding in the next phase. Second, treating housing purely as an asset class without sufficient attention to its role as essential infrastructure can create tensions between investment strategies and social needs. Third, coordination across levels of government and between housing, transport, labour, and climate policies is crucial if supply is to respond effectively where it is most needed.
For readers tracking global business, markets, and policy, Spain's housing market will remain an important barometer. It sits at the intersection of banking stability, construction activity, labour-market flexibility, and consumer spending, all of which influence broader economic performance. As Spain refines its mix of regulation, public investment, and private innovation, its success-or failure-in easing the housing supply crunch will carry implications well beyond its borders.
For those following related themes, housing intersects with broader reporting of economic trends, global market dynamics, banking and credit conditions, technology and proptech innovation, and sustainable development policy. As urbanisation, demographic shifts, and climate goals reshape real estate worldwide, Spain's evolving approach will remain a key case to watch.