
The Evolution of Business Lending in Modern Markets
How Business Lending Became a Strategic Engine for Growth
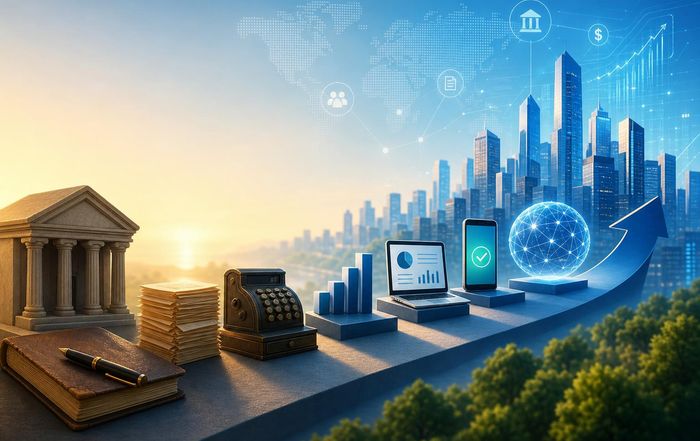
By 2026, business lending has moved far beyond the traditional image of a company executive sitting across a desk from a bank manager, waiting anxiously for a credit decision based on last year's financial statements. Across the United States, Europe, Asia and other key markets, the fusion of advanced data analytics, artificial intelligence, digital platforms and alternative capital sources has transformed how businesses access credit, how lenders assess risk and how capital flows through the global economy. For the readers of BizNewsFeed-many of whom are founders, finance leaders, investors and policymakers-this shift is not merely a technological story; it is a structural reconfiguration of how growth is financed, risk is shared and competitive advantage is created.
The evolution of business lending has been driven by several converging forces: the digitization of financial services, the rise of fintech challengers, the maturation of private credit, the tightening and recalibration of regulatory regimes, and the growing emphasis on sustainability and responsible finance. Each of these forces has reshaped the roles of banks, non-bank lenders, capital markets and technology providers, and together they have created a more complex, more data-driven and, in many cases, more inclusive lending ecosystem. Yet this evolution has also introduced new vulnerabilities, from cyber risk to model bias, and has raised questions about financial stability, regulatory perimeter and long-term credit quality.
For business leaders navigating this environment, understanding how lending has changed-and where it is heading-is now a core strategic competency. On BizNewsFeed, where coverage spans AI and automation, banking and capital flows, global markets and the broader economy, the evolution of business lending sits at the intersection of all these themes, shaping investment decisions, hiring plans and expansion strategies across continents.
From Relationship Banking to Data-Driven Credit
For much of the twentieth century and early 2000s, business lending in major markets such as the United States, United Kingdom, Germany and Japan was dominated by relationship-based banking. Corporate and commercial lenders at institutions like JPMorgan Chase, Barclays, Deutsche Bank and Mitsubishi UFJ Financial Group relied heavily on in-person relationships, qualitative assessments of management quality and a relatively limited set of financial metrics derived from audited statements and collateral appraisals. While this model provided stability and often deep local knowledge, it could be slow, opaque and exclusionary, particularly for smaller firms and newer ventures without long credit histories.
The global financial crisis of 2008 accelerated a shift that had already begun. As regulators tightened capital and liquidity rules and banks pulled back from some segments of commercial lending, businesses-especially small and medium-sized enterprises (SMEs) and growth-stage companies-found themselves searching for alternative sources of credit. At the same time, the rapid growth of cloud computing, application programming interfaces (APIs) and digital identity tools enabled new entrants to build lending platforms that could ingest and analyze far richer data sets than traditional underwriting models allowed.
The emergence of fintech lenders in the 2010s and early 2020s, such as Funding Circle, Kabbage (now part of American Express), OnDeck and a host of regional players across Europe, Asia and Latin America, demonstrated that it was possible to make near-instant credit decisions using real-time transaction data, accounting feeds, e-commerce performance metrics and alternative signals. This data-driven approach allowed for more granular risk segmentation and dynamic pricing, while also expanding access to credit for businesses that might previously have been deemed too small or too opaque. Readers can review broader trends in the digital transformation of finance in the technology coverage on BizNewsFeed, where lending innovation is increasingly intertwined with AI, cybersecurity and cloud infrastructure developments.
The Central Role of AI in Modern Business Lending
By 2026, artificial intelligence has become a foundational capability in business lending, used by global banks, regional lenders, fintechs and private credit funds alike. Machine learning models now power credit scoring, fraud detection, portfolio monitoring and even early-warning systems for covenant breaches or liquidity stress. Large institutions such as HSBC, BNP Paribas and Bank of America have invested heavily in AI-driven credit platforms, both to improve risk management and to deliver faster, more tailored experiences to business clients.
The use of AI in lending extends beyond simple regression models to encompass advanced techniques such as gradient boosting, deep learning and natural language processing. Lenders routinely analyze unstructured data-such as management commentary, industry news, supply chain disruptions and even legal filings-to refine their view of borrower risk. For a deeper exploration of how AI is reshaping financial decision-making, readers can learn more about AI in business contexts through dedicated analysis on BizNewsFeed.
At the same time, the rise of AI has prompted regulators and standard-setting bodies to focus on explainability, fairness and governance. Organizations such as the Bank for International Settlements and the Financial Stability Board have published guidance on the use of AI and machine learning in credit risk management, while national regulators in the United States, European Union, United Kingdom, Singapore and Australia have developed frameworks for model risk management and algorithmic accountability. Resources from institutions like the Bank for International Settlements offer insights into how supervisors are thinking about AI-driven credit models and their implications for financial stability.
From an operational perspective, lenders are increasingly combining AI with human expertise rather than replacing it. Credit officers and sector specialists use AI-generated insights as decision support, particularly for complex mid-market and large corporate credits where qualitative factors, strategic context and long-term relationships still play a decisive role. This hybrid model reinforces the importance of human judgment and sector knowledge, while leveraging AI to surface patterns and risks that would be difficult to detect manually.
The Expansion of Alternative and Private Credit
Another defining feature of modern business lending has been the rapid growth of non-bank and private credit. As regulatory capital requirements for banks have remained stringent, particularly in Europe and North America, institutional investors-pension funds, insurance companies, sovereign wealth funds and family offices-have increasingly allocated capital to private credit strategies managed by firms such as Blackstone, Apollo Global Management, Ares Management and KKR. These funds provide direct loans to businesses, often in the form of unitranche facilities, mezzanine debt or structured solutions tailored to specific transaction needs.
This expansion has been especially pronounced in the United States, United Kingdom and parts of Europe, where private credit has become a critical source of financing for leveraged buyouts, growth capital, recapitalizations and complex cross-border transactions. In markets such as Germany, France, the Netherlands and the Nordics, private credit has complemented traditional bank lending, offering borrowers more flexible covenant packages and execution certainty, albeit at a higher cost of capital. Analysts and market participants can track broader developments in this space through platforms such as S&P Global Market Intelligence and PitchBook, which regularly report on private credit fundraising, deployment and performance.
In Asia-Pacific, private credit has grown rapidly in countries including Australia, Singapore and Japan, and is gaining traction in emerging markets such as India, Thailand and Indonesia, where banks may be constrained by legacy non-performing loan issues or regulatory caps. In Africa and Latin America, development finance institutions and impact investors have played a prominent role in providing structured lending solutions, often tied to infrastructure, renewable energy and sustainable agriculture projects. For BizNewsFeed readers following global capital flows and emerging markets, the interplay between bank lending, private credit and capital markets has become a key lens for understanding corporate financing conditions and investment opportunities.
While the growth of private credit has enhanced choice and flexibility for borrowers, it has also raised questions about transparency, leverage and systemic risk. Because much of private credit operates outside the traditional banking system, data on exposures can be less comprehensive, and the resilience of these structures in a severe, synchronized downturn remains a focus of debate among regulators and economists. Institutions such as the International Monetary Fund and the OECD have examined these dynamics, emphasizing the need for improved data collection and risk monitoring across the non-bank financial intermediation sector.
The Digitalization of Lending Journeys and Embedded Finance
For many businesses, especially SMEs and digital-native companies, the most visible change in lending has been the digitalization of the entire borrowing journey. Instead of assembling paper-based applications and waiting weeks for a decision, companies can now apply online or through mobile interfaces, connect their accounting and banking data via secure APIs and receive decisions in hours or even minutes. This shift has been reinforced by open banking and open finance initiatives in regions such as the European Union, United Kingdom, Australia and parts of Asia, which mandate or encourage banks to share customer data securely with authorized third parties.
Embedded finance has taken this evolution a step further. Rather than approaching a bank or lender directly, businesses can now access credit at the point of need within the platforms they already use. E-commerce marketplaces, enterprise resource planning (ERP) systems, payment processors and logistics platforms have integrated lending offerings, often in partnership with banks or fintech lenders. Companies such as Shopify, Stripe, PayPal and Amazon have developed merchant lending and working capital solutions that draw on real-time sales and settlement data, enabling more dynamic and responsive credit lines.
This embedded model is particularly powerful in markets with large SME sectors and high digital adoption, such as the United States, United Kingdom, Canada, Australia, Singapore and South Korea, but it is also gaining ground in emerging economies where mobile and platform-based commerce leapfrogs traditional infrastructure. For business owners and finance teams, this integration reduces friction and paperwork, but it also requires careful management of vendor relationships, data privacy and dependency risks. The broader implications of embedded finance for competition and financial stability continue to be analyzed by bodies such as the World Bank, which tracks financial inclusion and digitalization trends across regions.
On BizNewsFeed, where readers follow business model innovation and funding trends, embedded lending is increasingly seen as a strategic differentiator for platforms and ecosystems. Those that can offer seamless, data-rich financing experiences may deepen their relationships with merchants and enterprise clients, while also opening new revenue streams and data monetization opportunities.
Crypto, Tokenization and the Edges of Business Credit
Although traditional bank and private credit still dominate business lending volumes, the last decade has seen the emergence of crypto-backed and tokenized credit structures that, while still relatively niche, are beginning to influence how some businesses think about financing. Decentralized finance (DeFi) protocols experimented with on-chain lending and collateralization, and while the volatility and regulatory challenges of early crypto markets limited mainstream adoption, several lessons have carried over into more regulated environments.
Tokenization of real-world assets, including corporate loans, receivables and trade finance instruments, has gained traction among forward-looking institutions and fintechs. By representing lending exposures as digital tokens on permissioned or public blockchains, lenders and investors aim to improve transparency, settlement speed and secondary market liquidity. Major financial institutions such as JPMorgan, HSBC and UBS have piloted or launched tokenization platforms, while regulators in jurisdictions like Singapore, Switzerland and the European Union have updated frameworks to accommodate digital asset experimentation within controlled parameters.
For founders, treasurers and CFOs tracking the intersection of crypto and corporate finance, the landscape remains complex and uneven across jurisdictions. BizNewsFeed maintains dedicated coverage of crypto and digital asset developments, helping readers differentiate between speculative experimentation and durable structural change. In markets such as the United States and United Kingdom, regulatory clarity around stablecoins, tokenized deposits and wholesale settlement systems is gradually improving, creating the possibility that, over time, some forms of business credit may be originated, traded and serviced on digital rails that coexist with or augment existing systems.
Sustainability, ESG and the Rise of Performance-Linked Lending
One of the most significant qualitative shifts in business lending has been the integration of environmental, social and governance (ESG) considerations into credit decisions and loan structures. Across Europe, North America and parts of Asia-Pacific, banks and institutional lenders have developed sustainability-linked loans (SLLs) and green loans that tie pricing to the borrower's performance on predefined ESG metrics, such as greenhouse gas emissions intensity, renewable energy usage, diversity and inclusion targets or supply chain traceability.
Major global banks including BNP Paribas, ING, HSBC and Credit Suisse (now part of UBS) have positioned themselves as leaders in sustainable finance, building dedicated ESG underwriting teams and frameworks. Borrowers ranging from large multinationals to mid-market industrials and real estate developers have used SLLs to align financing costs with their transition plans, while demonstrating commitment to investors, employees and regulators. For readers seeking to learn more about sustainable business practices and their interaction with finance, initiatives led by organizations like the UN Environment Programme Finance Initiative provide a useful reference point.
On BizNewsFeed, sustainability is not treated as an isolated theme but as a cross-cutting factor influencing corporate strategy, capital allocation and regulatory risk. In business lending, the integration of ESG has raised the bar for data quality and verification, as lenders must ensure that performance targets are credible, measurable and independently verifiable. It has also highlighted regional differences: European banks and borrowers have moved fastest, driven by the EU's sustainable finance taxonomy and disclosure rules, while adoption in the United States, Canada, Australia and parts of Asia is growing but more heterogeneous, influenced by local politics, sectoral composition and regulatory guidance.
For emerging markets in Africa, South Asia and Latin America, sustainable lending has often been catalyzed by multilateral development banks and blended finance structures that combine concessional and commercial capital. These arrangements aim to de-risk projects in renewable energy, resilient infrastructure and sustainable agriculture, while crowding in private lenders and investors. The evolution of these models will be critical to meeting global climate and development goals, and they underscore the increasing interconnectedness of business lending, public policy and long-term societal outcomes.
Regional Dynamics: How Markets Differ in 2026
While global trends in technology, regulation and investor behavior shape business lending everywhere, regional and national contexts remain decisive. In the United States, a deep capital market, a large and sophisticated private credit sector and a highly competitive banking industry create a broad spectrum of options for businesses, from revolving credit facilities and asset-based lending to unitranche and mezzanine structures. The Federal Reserve's monetary policy shifts over the early 2020s, including sharp rate hikes and subsequent recalibrations, have had a direct impact on borrowing costs, refinancing risk and covenant pressure, particularly for leveraged borrowers.
In the United Kingdom, the combination of global banks, challenger banks and fintech lenders has made the SME and mid-market lending landscape particularly dynamic, with open banking playing a central enabling role. Continental Europe, led by Germany, France, the Netherlands and the Nordics, remains more bank-centric but has seen strong growth in private credit and alternative lending, especially in the mid-market and sponsor-backed segments. The European Central Bank's policy stance, along with EU regulatory initiatives on digital finance and sustainability, continues to shape lending standards and product innovation.
In Asia, diversity is the defining feature. Japan's corporate lending environment is characterized by ultra-low rates and strong bank relationships, while South Korea, Singapore and Hong Kong have emerged as regional hubs for fintech lending, trade finance and structured credit. China's business lending system, dominated by large state-owned banks but increasingly influenced by digital platforms and regional banks, has undergone significant regulatory tightening, particularly around property-related exposures and shadow banking. Southeast Asian economies such as Thailand, Malaysia and Indonesia are seeing rapid growth in digital SME lending, often backed by regional tech platforms and global investors.
Africa and South America present a mix of high-growth opportunities and structural challenges. In countries such as South Africa, Nigeria, Kenya, Brazil and Colombia, mobile and platform-based lending has helped bridge gaps in SME finance, but macroeconomic volatility, currency risk and regulatory uncertainty can constrain longer-term credit. Development finance institutions and impact investors remain important players, often partnering with local banks and fintechs to expand access to working capital and project finance. For BizNewsFeed readers who follow global economic shifts and cross-border investment, these regional nuances are increasingly central to decisions about market entry, supply chain configuration and risk diversification.
Implications for Founders, CFOs and Corporate Strategists
The evolution of business lending in modern markets has direct implications for how founders, CFOs and corporate strategists think about capital structure, risk management and growth planning. In a world where credit is more data-driven, diversified and conditional on broader performance metrics, financial leadership requires a deeper integration of finance, technology, operations and sustainability.
Founders and growth-stage companies must navigate an expanded menu of financing options, from venture debt and revenue-based financing to embedded working capital lines and private credit solutions. Choosing the right mix requires not only an understanding of pricing and covenants but also of data-sharing requirements, platform dependencies and long-term relationship dynamics. Readers can explore these themes in more depth through BizNewsFeed's coverage of founders' journeys and funding strategies, where case studies and interviews often highlight how financing choices influence strategic flexibility.
For established mid-market and large corporates, the challenge lies in optimizing capital structures across cycles, managing refinancing risk in a higher-for-longer rate environment and aligning lending relationships with broader strategic priorities such as digital transformation, decarbonization and geographic expansion. Treasury and finance teams are increasingly expected to be conversant not only in traditional bank products but also in private credit, capital markets, ESG-linked instruments and, in some cases, tokenized or digitally native structures.
Across company sizes and sectors, one constant is the rising importance of data governance and financial transparency. As lenders rely more heavily on real-time data feeds and AI models, businesses that can provide clean, timely and well-structured financial and operational data will be better positioned to secure favorable terms and rapid approvals. This reality also influences talent strategies, with demand growing for finance professionals who are comfortable working alongside data scientists, technologists and sustainability experts. Readers tracking jobs and skills trends in finance and technology on BizNewsFeed will recognize how these evolving requirements are reshaping hiring, training and leadership development.
The Road Ahead: Trust, Resilience and Strategic Choice
Looking toward the remainder of the 2020s, the evolution of business lending will continue to be shaped by macroeconomic conditions, regulatory developments, technological breakthroughs and geopolitical dynamics. Periods of tighter financial conditions, such as those experienced in the early 2020s, will test the resilience of new lending models and the robustness of credit underwriting that leans heavily on recent performance data. At the same time, ongoing innovation in AI, data infrastructure and digital identity will create opportunities to further streamline lending processes, reduce fraud and extend credit to underserved segments.
For BizNewsFeed and its audience, the central narrative is one of choice and responsibility. Businesses have more options than ever in how they finance growth, manage liquidity and structure risk, but these choices come with new complexities and interdependencies. Lenders, whether banks, fintechs or private credit funds, must balance innovation with prudence, ensuring that speed and personalization do not come at the expense of sound risk management and fairness. Regulators and policymakers face the task of updating frameworks to reflect a more interconnected and technologically sophisticated lending ecosystem, without stifling beneficial innovation or driving activity into opaque corners of the system.
Ultimately, trust remains the cornerstone of business lending, even as algorithms and platforms mediate more of the interaction. Trust in data quality, in model governance, in counterparties' integrity and in the stability of legal and regulatory regimes will determine which lending relationships endure and which structures prove resilient across cycles. For companies operating across the United States, Europe, Asia, Africa and the Americas, cultivating that trust-through transparency, robust governance and strategic alignment with long-term partners-will be as important as negotiating basis points or covenant packages.
As BizNewsFeed continues to cover developments across business and markets, banking and credit, technology and AI and the broader global economy, the evolution of business lending will remain a central thread, connecting strategic decisions in boardrooms to policy debates in capitals and innovation labs around the world. For the business community, understanding this evolution is no longer optional; it is a prerequisite for building resilient, competitive and forward-looking enterprises in an increasingly complex financial landscape.